

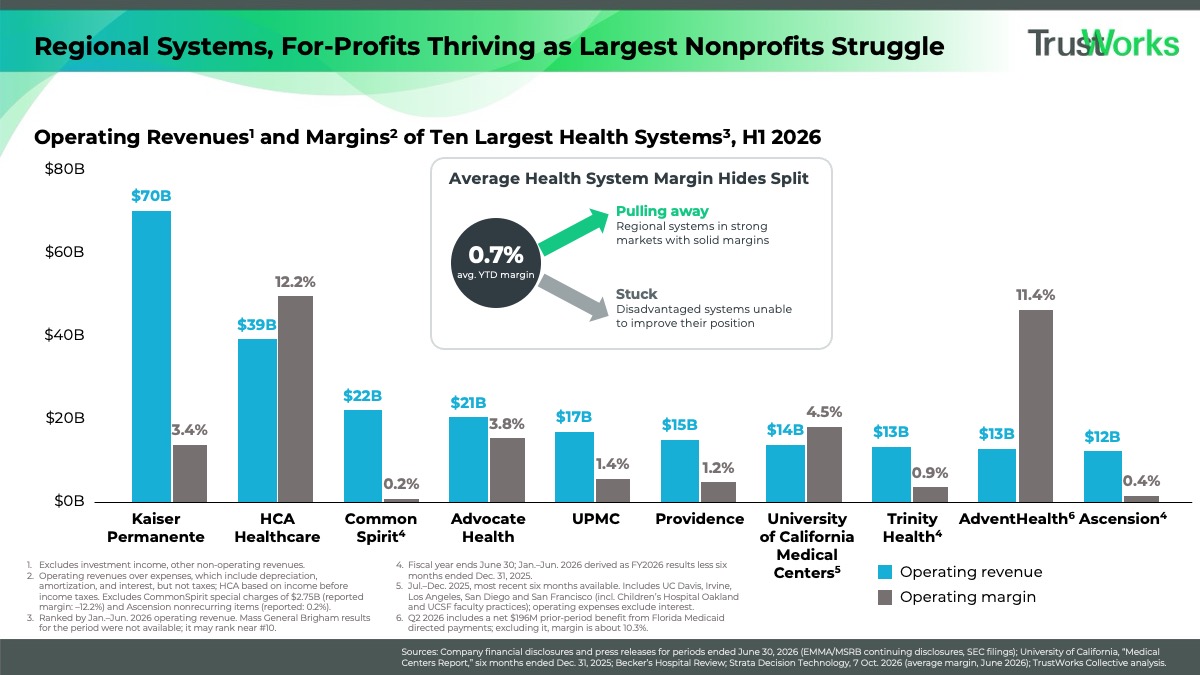
The median health system operating margin was just 0.7 percent as of June, but that thin measure hides a widening split. Among the largest systems by revenue, HCA Healthcare (12.2 percent) and AdventHealth (11.4 percent) posted double-digit operating margins in the first half of 2026, followed at a distance by Advocate Health (3.8 percent) and Kaiser Permanente (3.4 percent). At the other end, the multistate Catholic systems—CommonSpirit, Ascension, Trinity Health, and Providence—posted margins between 0.2 and 1.2 percent (CommonSpirit’s figure excludes $2.75B in special charges).
When we ran this analysis last year, four of the largest nonprofits lost money on operations in 2024. Setting aside CommonSpirit’s charges, none are in the red this time, but few generated a comfortable margin. Scale alone is not buying margin. The systems pulling away tend to combine cost discipline with concentrated positions in strong markets, like AdventHealth in Florida (although a one-time $196M Medicaid payment boosted its results). The “stuck” systems sprawl across markets where they rarely dominate; being big is not the same as being dominant or integrated. Industry averages can be deceiving: a 0.7 percent median papers over a few systems pulling away—and many more stuck in place.
From newsletter: Payer Party